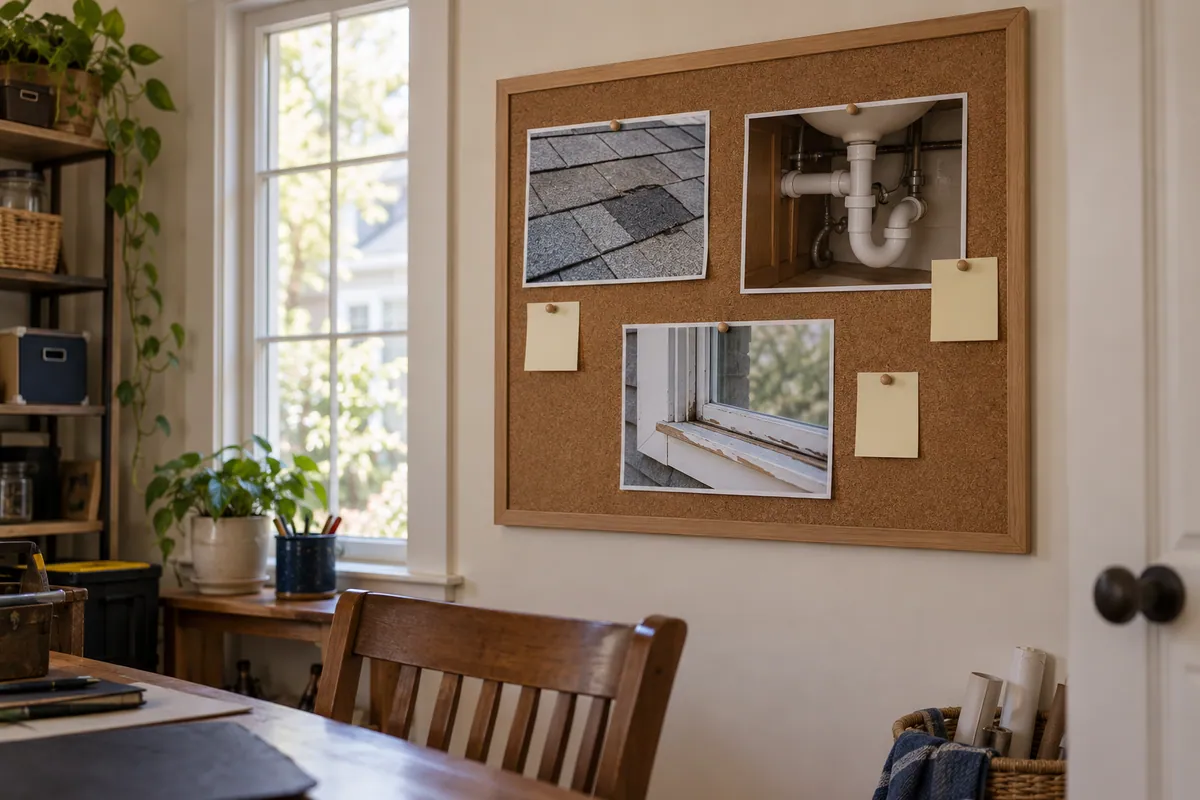
Start by separating events from claim records
Create a timeline of what actually happened before trying to summarize it as “several claims.” For each event, identify the loss date, property, cause, damaged areas, and insurer involved. Then list the claim numbers associated with it. Keep records from separate insurers visible instead of merging them into an unexplained total.
For example, roof and interior damage from one storm might appear in correspondence about different parts of a claim. An additional payment for that loss is not necessarily another event. Conversely, two leaks months apart should not be combined merely because both damaged the same room. Verify the insurer's records before describing either situation.
The question of a numerical cutoff is covered separately in how many home insurance claims is too many. Here, the goal is to explain the events together and find a suitable route for reviewing them.
Show which losses share a cause
Group the timeline by cause as well as date. This makes it easier to distinguish repeated failures from unrelated events. It also reveals where a repair explanation is missing. Use specific, documented descriptions rather than broad labels such as “water problems” or “bad weather.”
| Situation | Useful explanation |
|---|---|
| One event with several damaged areas | Identify the common event and match each record to its damage or payment. |
| Different events with unrelated causes | Describe each cause and the separate work completed afterward. |
| Repeated losses from one source | Explain what continued to fail and whether the source has now been corrected. |
| Unclear or disputed cause | Label the uncertainty and attach the findings available so far. |
Do not conclude that unrelated events must be accepted or that recurrence makes coverage impossible. The grouping supplies context; the insurer still applies its guidelines and applicable state rules.
Build one packet with a record for every event
Prepare a single overview that names each event and directs the reader to its supporting documents. Give documents recognizable names, such as the loss date followed by “plumbing invoice” or “claim closure letter.” Someone reviewing several losses should not have to guess which invoice belongs to which claim.
For each event, include the claim status, known payment, completed repair work, and remaining issues. Record claim closure and repair completion separately. A payment file can be closed while work remains unfinished, and a completed repair does not establish that every payment issue has been resolved.
If one project addressed multiple losses, explain the relationship. A plumbing replacement might address the cause of repeated leaks, while separate restoration invoices document different rooms. Attach the shared project record once and reference it from the affected events. Avoid counting the same work repeatedly as though it were several independent improvements.
Choose agency access that fits the combined history
Ask prospective agents whether they can evaluate homes with your combination of losses, current condition, and occupancy. Describe the actual circumstances early: for example, multiple repaired water losses with documented plumbing work, or a repaired fire loss followed by separate storm damage. The answer is more useful than a general promise to handle difficult insurance.
Ask which types of insurers or programs the agency can approach and whether a wholesale broker would be involved. An independent agency does not necessarily have access to every insurer, and a specialty designation does not establish access to a program suited to your home.
Keep a simple list of the insurers already approached, submission dates, and outstanding questions. If another agent proposes the same insurer, disclose the earlier submission and ask how to proceed. Coordinating the information helps avoid conflicting versions of your history without assuming that multiple agents always create a problem.
Ask which insurance routes remain worth reviewing
An admitted insurer with different guidelines may be one possibility. A specialty program may be another, but “specialty” does not by itself identify the company's regulatory status or the coverage form. Ask for the legal insurer name and the reason its program may fit the documented circumstances.
Eligible surplus lines insurers may provide another route when the admitted market does not accommodate the risk. Their policy terms and consumer protections differ, including the general absence of state guaranty association protection. Have the broker explain those differences for the proposed placement rather than treating surplus lines as an automatic next step after any decline.
A FAIR Plan or other residual market may also be relevant where available and when the property qualifies. Ask about the complete coverage arrangement and any additional protection needed. None of these routes guarantees acceptance based solely on an agency's willingness to submit the application.
Compare how each offer treats recurrence
For multiple-loss households, an important comparison is whether the proposed policy restricts the same kind of damage that has happened before. Ask specifically about exclusions, special limits, deductibles, and required mitigation connected to those losses. Request the relevant endorsement so you can review its actual scope.
Consider a proposal after several plumbing losses. Does a restriction apply only to known unrepaired damage, to a particular system, or more broadly to water damage? What does the policy say about a future sudden failure of a different pipe? Ask the agent to explain the wording without promising payment for a hypothetical loss.
Apply the same approach to each event in the timeline. An offer addressing the water concern might also contain a roof limitation that matters because of a separate roof claim. Evaluate the combined effect rather than accepting a policy because it resolves only the most recent obstacle.
Coordinate old claims with new underwriting
When different insurers handled previous events, request the relevant records from each. Maintain separate claim contacts and deadlines. A prospective insurer's questions about the home do not transfer responsibility for an earlier loss or replace your duties under the policy that applied when it happened.
If additional damage is discovered during repairs, explain what is known and what remains under evaluation. Do not assign it to a convenient event merely to simplify the history. Ask the relevant adjuster or professional to document the findings, then update the agent evaluating future coverage.
Check any specialty consumer report for factual errors, including duplicate entries or mismatched addresses. CLUE can report up to seven years of home claims information, which is different from an insurer's underwriting review period. Share evidence of a pending dispute and avoid representing an unresolved correction as complete.
Use the review to identify the next useful step
Ask the agent to summarize which options are being reviewed, which questions remain, and what information would move each submission forward. The next step might be obtaining an old insurer's status letter, clarifying whether events are related, or documenting a shared repair. This is more actionable than collecting repeated declines without an explanation.
If a current policy is ending, distinguish cancellation before expiration from nonrenewal at the end of the term and provide the written deadline. Otherwise, organize the search around your actual renewal and coverage needs. In either case, a quote or application is not active insurance. Obtain written confirmation of binding before relying on replacement coverage.
Continue with a related guide
Frequently asked questions
How should I present several claims to an agent?
Provide one event timeline supported by a separate record for each loss. Include the cause, date, insurer, claim status, payment if known, and repair status. Explain relationships between events and shared repair work so the reviewer can understand the whole history without reconstructing it from scattered documents.
Can one event appear in several insurance records?
Yes, records can concern different aspects of an event, including correspondence or additional payments. Check the actual claim numbers and insurer descriptions before treating them as separate losses. If you find a duplicate or inaccurate entry, request clarification and dispute the factual error with supporting evidence.
Should unrelated claims be explained separately?
Yes. State the cause and repair for each event rather than grouping everything under a broad damage label. Unrelated events do not guarantee eligibility, but a precise explanation gives the insurer better information than an unexplained claim total and helps identify which questions still need answers.
What if one repair project addressed several prior losses?
Identify the project once and explain which losses it addressed. Attach the contractor's scope, completion information, and other relevant evidence, then connect those documents to each affected event. Distinguish repairs to damaged rooms from work intended to correct the source of repeated losses.
Can different agencies have different options for multiple claims?
They may have different insurer appointments or access through brokers, but ask about access relevant to your particular circumstances. No agency automatically represents the entire market. Tell a new agent which insurers have already reviewed the home so submissions use consistent facts and any overlap can be addressed.
Does repeated water damage mean every new policy excludes water?
No universal rule establishes that result. Ask about the actual offer's water terms, special limits, exclusions, and mitigation requirements. Read the endorsement and have the agent explain its scope, including whether restrictions extend beyond the previously damaged area or component.
How do I handle claims from more than one insurer?
Keep each insurer's records, contacts, and deadlines separate while bringing the event summaries into one timeline for shopping. The new insurer evaluates proposed future coverage; it does not automatically take over old claims. Update the agent when claim status, repair information, or documented facts change.
What if several insurers decline the combined history?
Ask which reasons were given and whether missing information or a documented correction could change the review. Discuss other suitable admitted, specialty, or eligible residual-market routes with the agent. Compare any available offer's restrictions carefully, and do not treat further submissions as a promise that coverage will be offered.
Consumer resources
These resources provide background. State-specific examples do not create a nationwide rule.